

How Finding a Roofing Company with 0 Financing Works in 2026
Finding a roofing company with 0 financing in 2026 is one of the most effective strategies for securing a full roof replacement or urgent repair without depleting your liquid savings. In current economic conditions, contractor-sponsored promotional financing acts as an accessible line of credit provided through specialized third-party home improvement lenders.
The mechanics behind zero percent financing are straightforward. Rather than acting as a bank ourselves, a certified roofing contractor partners with specialized sales finance organizations. When a contractor offers a zero percent interest deal, the installer absorbs an upfront lender fee—often called a dealer fee—to buy down the interest rate on your behalf. This allows you, the homeowner, to access interest-free capital over a set promotional period.
Modern application processes have evolved far beyond cumbersome bank paperwork. Thanks to rapid digital processing, pre-qualification checks take fewer than 60 seconds online using soft credit inquiries that carry zero impact on your credit score. Once you accept an offer, full formal approval routinely takes place the exact same day.
This speed is crucial when dealing with emergency roof leaks in Southeastern Michigan. When storm damage, severe ice dams, or failing shingles strike homes in Oakland County or Wayne County, waiting three to six weeks for a traditional bank loan or home equity loan is simply not an option. Immediate approval means materials can be ordered and work can be scheduled within 24 to 48 hours, shielding your home’s interior from costly secondary water damage.
Understanding 12-Month vs 18-Month Same-As-Cash Terms
When shopping for a roofing company with 0 financing, you will primarily encounter two promotional term lengths: 12-month and 18-month “same-as-cash” plans.
- 12-Month 0% Interest Plans: Often referred to as standard same-as-cash loans, these are widely used for emergency repairs or standard shingle replacements. Under this structure, your principal balance is divided across 12 monthly payments—or structured with optional minimum payments—with zero accrued interest during the 365-day promotional window.
- 18-Month 0% Interest Plans: Frequently paired with $0 down payment incentives, an 18-month term offers a longer runway to spread out costs. For a major overhaul—such as a $12,000 to $18,000 architectural shingle replacement—an 18-month timeframe reduces the required monthly allocation to keep your budget balanced.
Both formats operate on the guarantee that if you pay off the full principal balance prior to the expiration date, you pay zero dollars in interest charges.
Qualifications for 0% Interest Roof Loans
While zero percent financing is widely accessible, approval is not automatic. Lenders evaluate several core criteria to mitigate risk on unsecured home improvement lines:
- Credit Profile: While standard long-term financing plans accept fair credit scores (around 600–640), 0% interest promotional plans typically require prime credit scores starting around 680 to 720+.
- Income Verification: Lenders verify steady income via W-2s, pay stubs, or tax returns to confirm your ability to manage monthly installment requirements.
- Debt-to-Income (DTI) Ratio: Lenders review your total monthly debt obligations relative to gross income. If your individual credit profile is on the border, incorporating co-applicant or spouse earnings can lower the total household DTI and drastically boost approval odds.
- Soft Credit Pre-Qualification: Trustworthy contractors offer soft-pull online tools, allowing you to view eligible loan structures and rate tiers prior to submitting a formal credit application.
Comparing Zero Percent Financing to Personal Loans and HELOCs
Evaluating funding options is essential before signing a home improvement contract. While contractor-sponsored 0% financing provides unmatched short-term interest savings, long-term loan structures might better suit homeowners looking for multi-year payment terms.
Unsecured personal bank loans are another option, though APRs generally range between 6% and 36% based on your credit tier. Personal loans carry no collateral risk to your home, but accrued interest accumulates immediately from day one.
Home Equity Lines of Credit (HELOCs) and Home Equity Loans leverage your home’s accumulated value as collateral, offering lower fixed or variable interest rates over 10- to 20-year terms. However, HELOCs involve formal home appraisals, substantial closing fees, and lengthy 3- to 6-week processing timelines that render them impractical during emergency roofing situations.
In some regions, property owners explore specialized energy programs like Ygrene PACE financing, which allows 100% roof financing backed by property equity rather than credit scores, repaid directly through property tax assessments. However, for most residential projects, contractor-arranged loans remain the fastest route. To learn more about navigating these choices, explore Consumer Financial Protection Bureau guidance on HELOCs or review our guide on Ultimate Roof Financing Options.
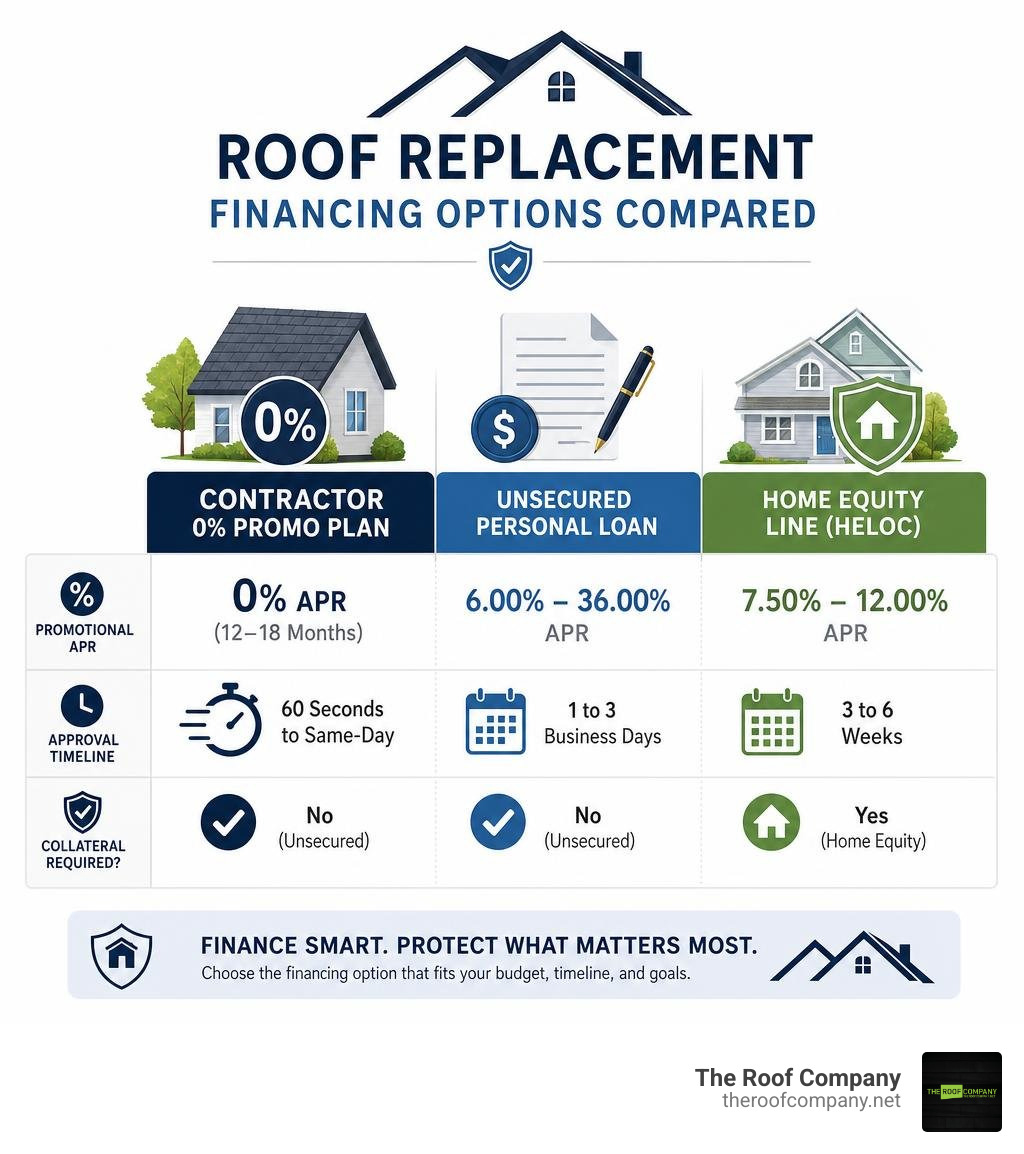
| Financing Feature | Contractor 0% Promo Plan | Unsecured Personal Loan | Home Equity Line (HELOC) |
|---|---|---|---|
| Promotional APR | 0% APR (12-18 Months) | 6.00% – 36.00% APR | 7.50% – 12.00% APR |
| Approval Timeline | 60 Seconds to Same-Day | 1 to 3 Business Days | 3 to 6 Weeks |
| Collateral Required? | No (Unsecured) | No (Unsecured) | Yes (Home Equity) |
| Upfront Closing Costs | $0 | Varies ($0-$200) | High ($300-$1,500+) |
| Best For… | Rapid repairs & full payoffs within promo window | Moderate projects needing 2-5 year terms | Large overhaul projects needing 10+ year repayment |
Understanding these distinctions helps prevent financial surprises down the road. For detailed safety steps when evaluating loan structures, check out our Guide to Financing a New Roof Safely.
What to Watch Out For: Fine Print and Deferred Interest

Zero percent financing is a fantastic tool, but you must read the fine print carefully. The single biggest trap in promotional financing is deferred interest.
Unlike a standard 0% APR loan where interest is simply waived during the promotional window, a deferred interest loan calculates monthly interest silently in the background from the very first day of the contract. If you pay off 100% of the loan principal before the promotional period ends (e.g., 12 or 18 months), that accumulated interest is permanently waived.
However, if even $1.00 of principal remains unpaid when month 19 arrives—or if you miss a required monthly payment—the lender triggers a clause that retroactively adds all accumulated interest back to your principal balance at a high standard APR (frequently 17.99% to 29.99%).
To safeguard your finances:
- Confirm whether the contract is true 0% APR or deferred interest.
- Divide your total balance by the number of promotional months (minus one month for safety) to set up automatic payments.
- Ensure there are zero pre-payment penalties so you can clear the balance as quickly as you choose.
Finding a Transparent Roofing Company with 0 Financing Options
A reputable contractor will never hide promotional fine print. When evaluating contractors across Novi, South Lyon, or anywhere in Oakland and Washtenaw Counties, look for full transparency regarding pricing.
Some disreputable installers mark up their base price by 10% to 15% when a customer asks for 0% financing to cover the dealer fee charged by the lender. A trustworthy roofing company with 0 financing keeps cash prices and financed prices completely clear and consistent. Before signing, ask for an itemized estimate breaking down labor, tear-off expenses, system components, and permit fees. You can get a baseline of local investment expectations by checking our breakdown of Average Roof Replacement Costs.
Protecting Warranties When Using a Roofing Company with 0 Financing Plans
Homeowners sometimes ask: Does choosing 0% financing compromise the quality of my roof materials or warranty protection?
The short answer is absolutely not. Payment method has zero bearing on the material grade installed or the manufacturer warranty issued. When you partner with certified contractors, your roof replacement carries identical lifetime workmanship guarantees and 50-year non-prorated material warranties (such as GAF or CertainTeed complete system warranties) regardless of whether you pay with cash, a standard loan, or 0% promotional financing. Lenders disburse full project funds directly to the contractor only after you sign off on a completion certificate confirming the job was installed to your complete satisfaction.
Bundling Roof Replacement with Gutters and Home Upgrades
When establishing a 0% promotional loan, bundling multiple exterior projects into a single application is often a smart move. Modern contractor financing agreements allow you to group related exterior improvements—such as new seamless gutters, gutter guards, soffit and fascia repairs, or attic insulation upgrades—under one zero percent umbrella.
Executing a roof replacement without updating worn-out, clogged gutters risks immediate water spillover that can damage your fresh fascia boards and foundation landscaping. Bundling these services delivers key benefits:
- One Application & Approval: Eliminates the hassle of running multiple credit checks or juggling different payment due dates.
- Lower Overall Labor Costs: Contractors can install gutters, drip edges, and attic insulation while scaffolding and safety equipment are already set up on-site, cutting down overall mobilization fees.
- Optimal Energy Efficiency: Coupling a new ventilated roof deck with upgraded attic insulation preserves indoor climate control and lowers seasonal energy bills throughout Southeastern Michigan winters and summers.
For a broader breakdown of local installation pricing and material bundling choices, explore our detailed breakdown on Michigan Roof Replacement Cost Factors.
Frequently Asked Questions about 0% Roof Financing
Can I get 0% roof financing with fair credit?
While prime credit scores (typically 680+) give you the highest chance of securing 0% promotional APR offers, fair credit applicants are not automatically excluded. If your credit score sits in the 600–660 range, lenders often evaluate overall household income and existing debt obligations. Adding a co-applicant or spouse with stable earnings to your application can significantly lower your debt-to-income (DTI) ratio, helping you qualify for interest-free terms. If 0% plans remain out of reach, low fixed-APR options (such as 4.99% to 9.99% terms spanning 5 to 12 years) provide manageable monthly installments without straining your budget.
How fast can roof replacement work begin after financing approval?
Thanks to modern mobile application tools, pre-qualification decisions take as little as 60 seconds, with formal digital loan approval usually landing the same day. Once financing approval is locked in, material ordering and crew scheduling happen rapidly. For standard projects across Southeastern Michigan, physical installation can start within days. In urgent emergency leak situations, crews can be dispatched within 24 hours to dry in the roof deck and initiate full repairs immediately after approval confirmation.
What happens if I do not pay off the balance before the 0% promo period ends?
What happens next depends on whether your contract features true 0% APR or deferred interest:
- True 0% APR Plans: Any remaining balance at month 13 or 19 begins accruing interest moving forward at the standard contractual rate. You will not owe back-interest for the promotional period.
- Deferred Interest Plans: If any balance remains when the promo window closes, the lender retroactively calculates and adds all accumulated interest from day one onto your remaining principal balance. To avoid this, calculate your exact monthly payment by dividing the total balance by one month less than the full promotional term.
Conclusion
Finding an honest roofing company with 0 financing allows you to protect your home’s structure immediately while keeping your cash working for you. Whether you are addressing storm damage in Oakland County or upgrading an aging shingle roof in Washtenaw or Wayne County, zero percent same-as-cash options remove price friction without compromising installation standards or warranty strength.
At The Roof Company, we bring transparency, lifetime guarantees, and straightforward guidance to every project across Southeastern Michigan. If you are ready to explore stress-free payment options tailored to your household budget, read our advice on Hiring a Reliable Roofing Contractor or go ahead and Schedule your roof replacement today for a free, transparent estimate!


